How to Compete With Cash Buyers When You Have a Low Down Payment (Orange County Buyers)
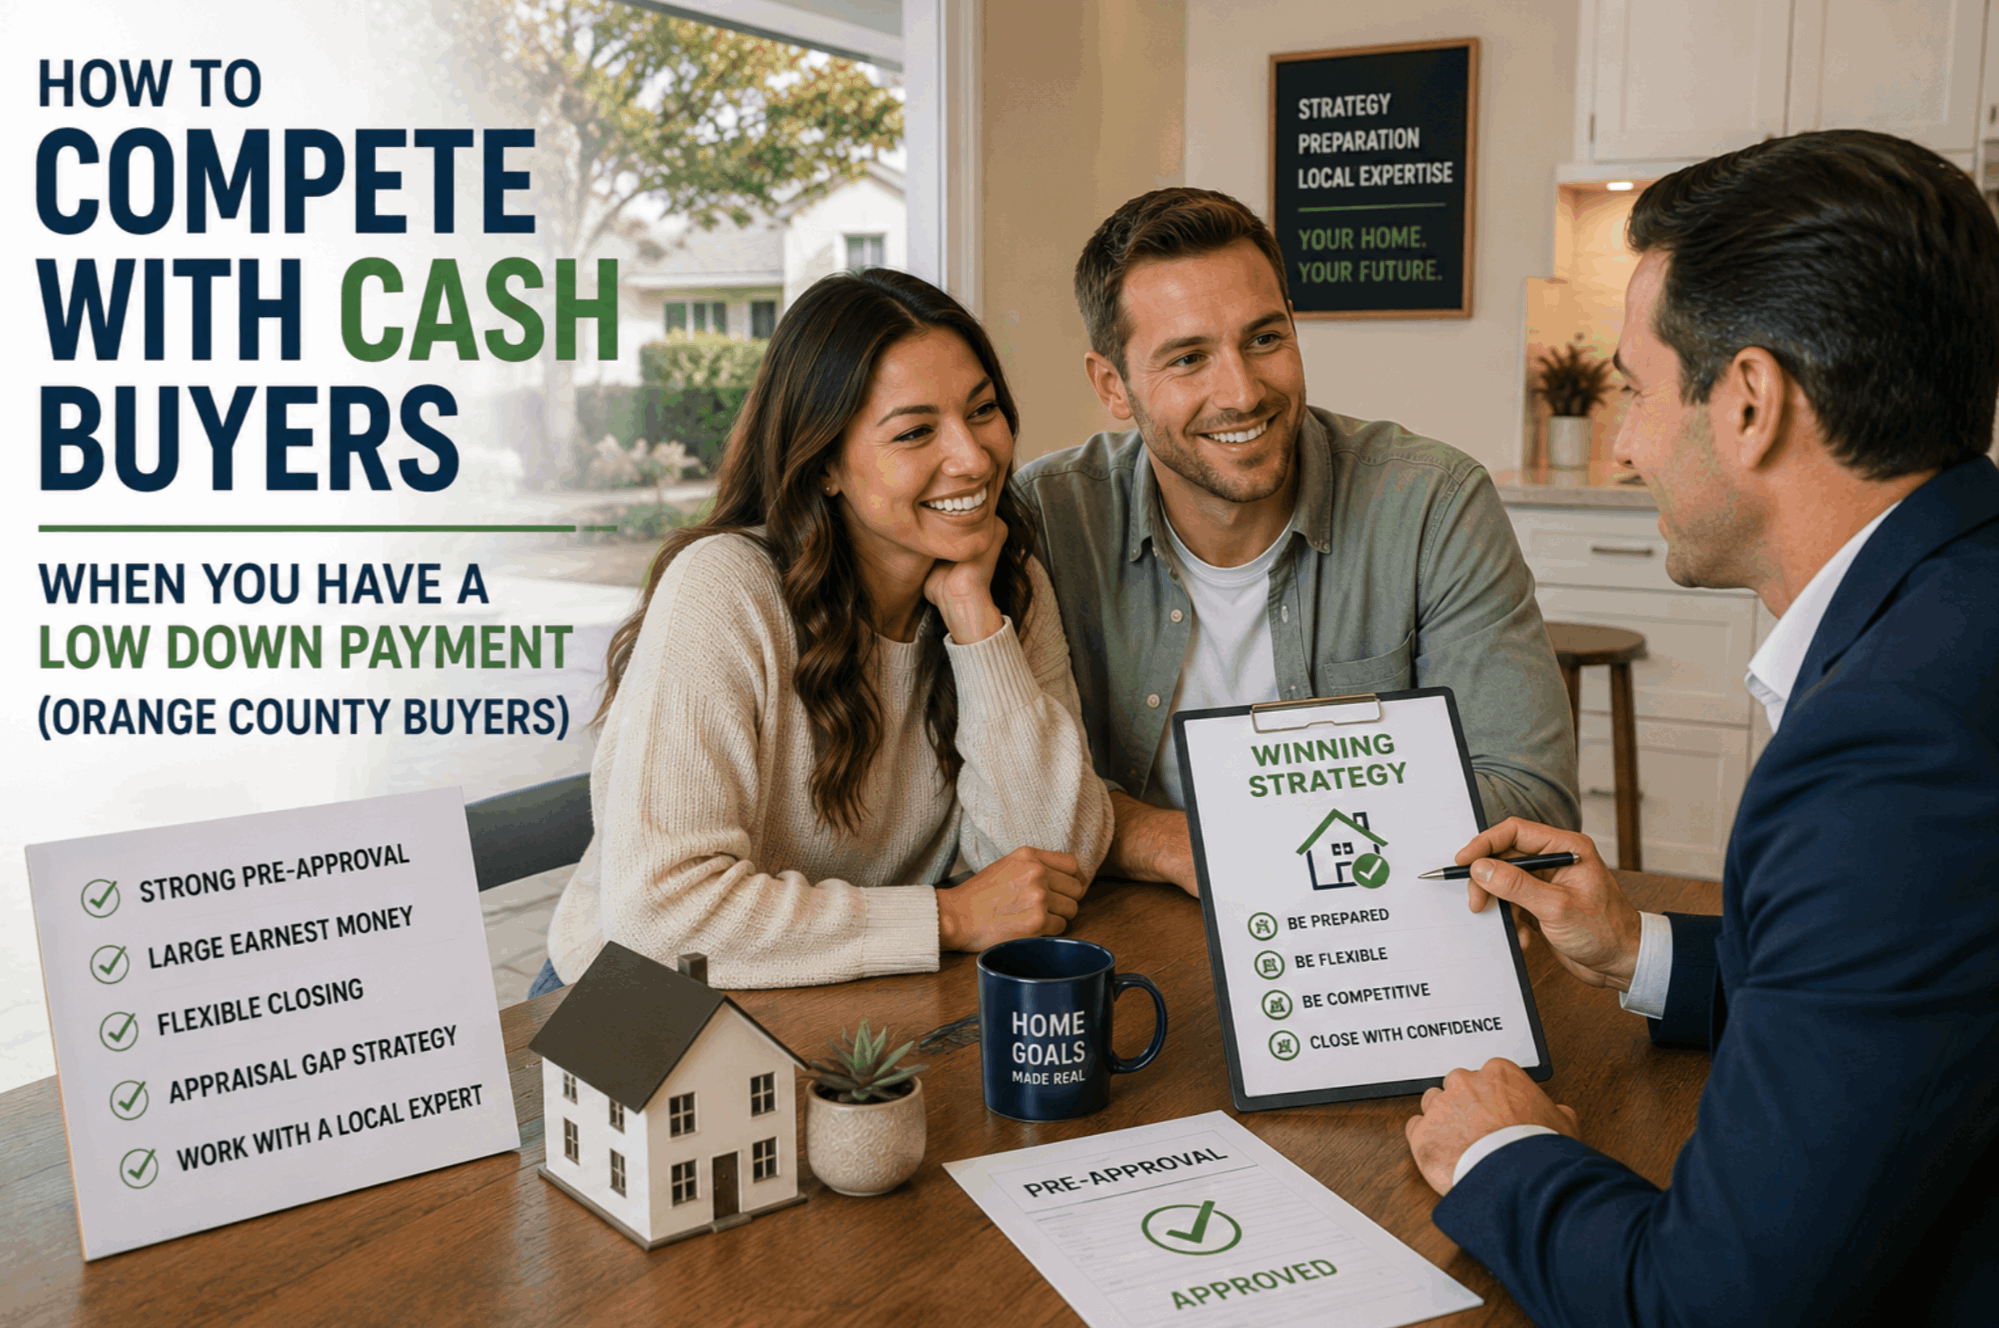 How to Compete With Cash Buyers When You Have a Low Down Payment (Orange County Buyers)
A few months ago, I spoke with a young couple looking to buy their first home in Orange County. They had good jobs, solid credit, and about 10% saved for a down payment. They found a home they loved, made a strong offer, and felt confident.
Two days later, they got the call:
“The seller went with another buyer.”
Same price.
Same terms.
But the other buyer was cash.
They asked me, “Is there anything we could have done differently?”
The answer was yes—and this is where most buyers are never properly guided.
Why Low Down Payment Buyers Are at a Disadvantage
If you’re buying a home with a low down payment—3.5%, 10%, or even 20%—you are at a clear disadvantage when competing against cash buyers or buyers with very large down payments.
The reason is very simple:
the seller is looking for the buyer who is the least risky and most likely to complete and close the transaction.
In competitive Orange County markets, sellers care about certainty just as much as price. A loan contingency introduces risk, delays, and uncertainty—and sellers want to avoid that.
The Real Problem Isn’t the Down Payment
Most buyers assume their down payment is the issue.
It’s not.
The real issue is financing risk.
From a seller’s perspective, a buyer with a loan can:
-
Lose approval late in escrow
-
Run into lender delays
-
Fail to close on time
That’s why cash offers often win—even when financed buyers offer more money.
The Strategy That Levels the Playing Field
The key is to secure a fully underwritten loan before making an offer.
This is not a standard pre-approval.
A fully underwritten loan means:
-
Your income, assets, and credit are already reviewed
-
Your file has gone through underwriting in advance
-
You can confidently remove the loan contingency
When this happens, the seller no longer sees you as risky.
Your offer begins to compete directly with cash buyers.
Why This Is Critical for Homes Under $1.5 Million
If you’re buying a starter home under $1.5M in Orange County, competition is intense. These homes attract:
-
Cash buyers
-
Investors
-
Buyers with large reserves
In this price range, having a fully underwritten loan is not optional.
It WILL make the difference between losing the home and getting your offer accepted.
How We Help Buyers Win
This is exactly where our role comes in.
We help buyers:
-
Get connected with the right lender
-
Secure a fully underwritten loan
-
Position their offer as low-risk and highly competitive
This isn’t about luck.
It’s about preparation, strategy, and removing uncertainty for the seller.
Frequently Asked Questions
Can a buyer with a low down payment really compete with a cash offer?
Often, yes. Sellers are weighing certainty as much as price. When your loan has already been through underwriting and you can remove the loan contingency, your offer carries much less risk and can compete directly with cash.
What is the difference between a pre-approval and a fully underwritten loan?
A standard pre-approval is a lender's initial review of your finances. A fully underwritten approval means an underwriter has already verified your income, assets, and credit, so the main remaining items are the property itself, such as the appraisal and title.
Is it risky to remove the loan contingency?
It can be, because if the loan falls through you may put your deposit at risk. That is exactly why the underwriting should be done before you write the offer, and why you should review the risk with your lender and agent first.
Why does this matter most for homes under $1.5 million in Orange County?
Starter homes in that range draw the most competition from cash buyers, investors, and buyers with large reserves. A low-risk financed offer is often what separates a winning offer from a losing one there.
How long does it take to get fully underwritten?
It depends on the lender and how quickly you provide documents, but plan on starting well before you begin touring homes seriously so you are ready to write a strong offer on day one.
References
- Consumer Financial Protection Bureau, Buying a House
- Consumer Financial Protection Bureau, Understand Loan Options
- California Housing Finance Agency (CalHFA)
Click Here to Make an Appointment With Dar Mardan
Let’s use this information to protect you—and put you in a position to win.
Categories
- All Blogs (63)
- Buy home (12)
- buy home insurance (2)
- buyer agent (1)
- divorce (5)
- downsizing (17)
- estate planning (12)
- Estate Real estate (6)
- First time home buyer (5)
- home buying advice (6)
- Home buying tips (8)
- Home inspection (3)
- Home Inspections and Repairs (2)
- home insurance (1)
- home selling advice (15)
- Home Selling Tips (34)
- Home upgrades (2)
- how to sell your home (13)
- Lower home insurance cost (2)
- Lower insurance premiums (1)
- market update (3)
- Newport Center (1)
- Orange county homes (46)
- Pre Listing Preparation (7)
- probate sale (4)
- proposition 19 (4)
- Realtor tips (13)
- Rental Income (1)
- retirement planning (10)
- ROI upgrades (2)
- seller agent (1)
- Selling tips (9)
- transfer tax basis (2)
Recent Posts